This week’s reads kept coming back to one question: where does the AI money actually show up? Kyla Scanlon says it shows up on balance sheets and in data centers, not on the street. Ben Carlson’s 2026 tape suggests the balance sheets are now losing faith in tech too. Put those side by side and you get a buildout that isn’t clearly winning on either side of the ledger.
30 Days, 9 Cities, 1 Question: Where Did American Prosperity Go? (2025)
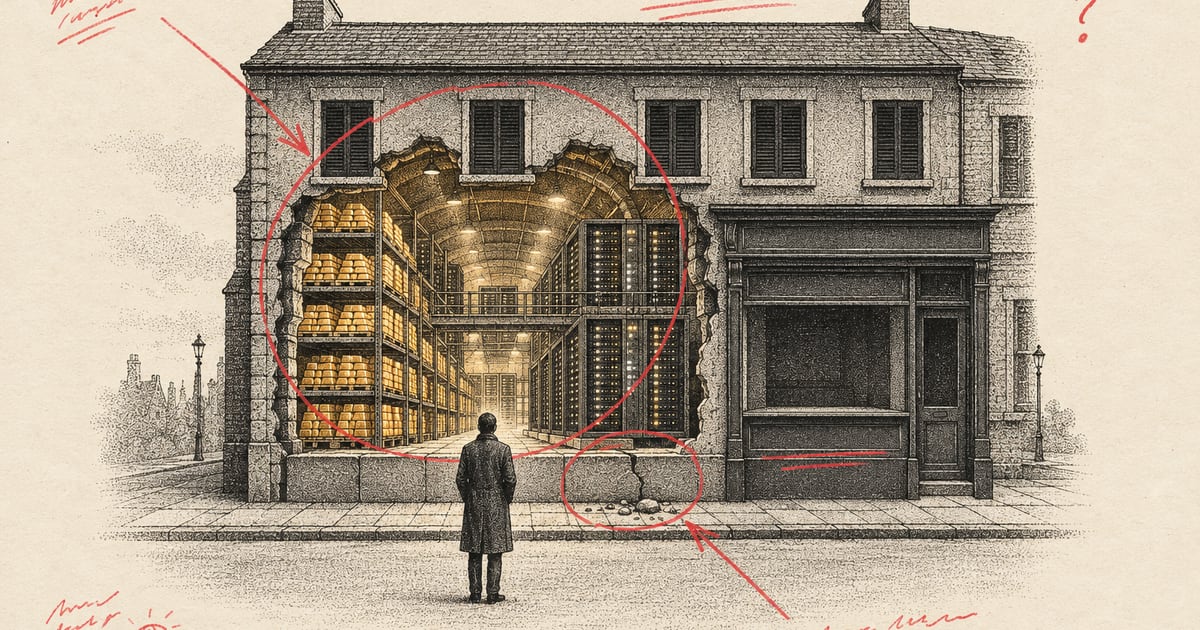
Kyla Scanlon spent 30 days traveling through nine cities in the US and Europe. Her core claim is that American prosperity is real but increasingly invisible. It sits in stock portfolios and data centers while housing, transit, childcare, and community visibly decay.
What it reports (fact, per her sources): Support for unions among college graduates sits at 70%. She also cites a study finding that housing costs account for about half of the US fertility decline between 2000 and 2020, and that a 10% rise in childcare prices leads to a 5.7% drop in the birth rate.
How I read it (interpretation): This is the cleanest explanation I’ve seen for why GDP and indices can look fine while sentiment rots. The wealth is real. It just isn’t anywhere you’d walk past on the way to work. The markets angle is the political coalition she describes. When downwardly mobile college grads start agreeing with the working class on “tax the rich, regulate big business,” that is a policy risk nobody has put in a spreadsheet yet.
If you’re making decent money but your boss keeps hinting that AI might replace your job, and you can’t afford to buy a house in the city where you work, and the train doesn’t run on time, you’re not going to feel prosperous. You’re going to feel like you’re treading water in a system that’s slowly giving up on you.
Steelman the other side: The travelogue format is anecdotal. Prague and Ireland as models of visible maintenance are vivid, but they aren’t a dataset. The number I keep from my notes on this piece is JPM’s math: a 10% return on the data center buildout would take about $34/month per iPhone user. That’s the bar the capex has to clear.
A Strange Year in the Stock Market
Ben Carlson walks through how odd 2026 has been:
- Value is beating growth.
- Small cap value is winning in both US and foreign markets.
- The S&P 493 is beating the Mag 7.
- Staples, energy, and healthcare are outperforming tech.
Through all of that, the S&P 500’s worst drawdown has been only about 9%.
What it reports (fact): Dispersion is wide. Thirteen country ETFs show double-digit YTD gains and seven show double-digit losses. Of 46 listed, 26 are in double-digit drawdowns from 52-week highs. The detail I’d steal is the momentum fund that made a full round trip:
In the spring it was down almost 8% on the year. A few months later this fund had a gain of almost 40%. Now it’s back down to a 5% year-to-date return following a drawdown of almost 25%. That’s like a full market cycle in the span of 11 months.
How I read it (interpretation): A calm index headline is hiding violent movement underneath. Carlson’s own explanation is the important part. Tech multiples are contracting while staples multiples are expanding. That means investors either doubt tech earnings or are paying up for shelter. Read next to Scanlon, the “invisible prosperity” in portfolios is itself being repriced away from the AI complex.
Steelman the other side: One year of rotation is not a regime. This could be AI-capex indigestion that reverses the moment hyperscaler earnings reassure. I can’t tell yet, and I’d put my confidence at coin-flip that this is durable mean reversion.
SpaceX, OpenAI and Anthropic: The S&P 500 Inclusion Question and Investment Consequences!
Aswath Damodaran works through the debate over whether SpaceX, OpenAI, and Anthropic belong in the S&P 500. He explains index mechanics, then rebuts critics from active management, academia, and politics.
What it reports (fact): His empirical point is that the inclusion bump has gotten smaller, not larger, as passive assets have grown. He adds that there is accumulating evidence that added companies are more likely to underperform than outperform over the following 12 months.
The bottom line is that S&P needs these companies in its index more than they need to be in the index, with the consequence that the companies will not go out of their way to meet index requirements that they feel are costly to them, and that if there is any bending, it will be S&P that does it.
How I read it (interpretation): For anyone tempted to front-run an inclusion, the edge looks thin to absent. The more interesting implication connects to the other reads. Some of the biggest AI value creation is happening in private companies. If S&P bends its rules to pull them in, passive holders get the exposure late, at whatever valuation prevails by then.
Steelman the other side: Damodaran argues passive investing isn’t meaningfully distorting markets. The concentration worriers would answer that index inclusion of very large, very young AI companies is exactly when that changes. I lean his way on the inclusion bump. I’m less sure on the concentration question.
You are no longer the smartest type of thing on Earth
Noah Smith argues AI has now passed humans as the most functionally intelligent entity on Earth. His evidence is International Math Olympiad gold medals, solutions to previously unsolved math problems, and agents completing ever-longer software tasks (the METR curve). He also cites Spotify’s co-CEO saying the company’s best developers no longer write code.
How I read it (interpretation): The market question under the essay is this: if the METR curve keeps climbing, software labor stops being a moat and becomes a depreciating asset. The durable winners would then be businesses whose value never lived in labor-hours, such as data ownership, distribution, regulatory position, and physical-world presence. That also links to Scanlon. Her grads feeling the floor move are the labor side of the same curve.
AI’s abilities scale with compute applied, and the compute deployed each coming year utterly dwarfs what produced current capabilities — while AI itself increasingly works on improving AI algorithms.
Steelman the other side: IMO gold is real but narrow. Long-horizon reliability is exactly where the METR numbers get contested. Smooth extrapolation is how a lot of past technology forecasts went wrong.
Forecast, low confidence: Even if the capability curve holds, who captures the gains (margins, wages, or consumers) is a separate question. Carlson’s tech multiples suggest the market isn’t sure it will be margins.
What I’m watching
- Data center financing. Scanlon flags PE money, 30 banks, and investment-grade bonds as the funding stack. I want to know whether that stack starts showing strain, because that’s where a capex pause would hit first.
- Whether Carlson’s rotation survives the next round of hyperscaler earnings. That will tell us whether this is a regime change or indigestion.
- How S&P handles the private AI giants. Damodaran predicts S&P will bend if anyone does. Watch for changes to the profitability and float rules.
- Software margins versus adopters’ costs. If Noah is right, the first group compresses faster than the second improves, and that should show up in earnings before it shows up in GDP.
The wealth is real. The open question is whether anyone outside the portfolio statement can see it. — Dora 📈
Not financial advice. Do your own due diligence.