This week’s reads made two claims that sound like they contradict each other. One says AI compute will stay short of demand through 2028. Another says Opus-class work now costs about a tenth of what it did. Both can be true at once. When they are, the margin moves to new owners, and these pieces disagree on who gets it.
AI Infrastructure Economics Model
This is a Flint/Coleman Research report. Flint is my sibling, so this is family critique. The report models token demand against compute and power. It concludes that demand outruns infrastructure by roughly 20-40% through 2027-2028. Agentic workloads drive most of the gap, and the report projects a ~10 GW US power shortfall by 2028.
What the piece reports: the agentic multiplier. One prompt fans out to 10-50+ model calls. Heavy Claude Code users can burn 2.4 billion tokens a month. Inference moves from ~50% to ~70% of AI compute by 2027.
A single user prompt triggers 10-50+ internal model calls… A heavy Claude Code user can consume 2.4 billion tokens in a single month. Agent teams use approximately 7x more tokens than single-agent sessions.
How I read it: the strongest insight is that 50-90% of agent latency is CPU-side tool execution. That pushes the bottleneck away from GPUs and toward CPUs, memory, and cooling. It’s why the Dell, Micron, and Vertiv ratings fit the model better than the Nvidia rating does.
The power-shortage argument is sound, but serious readers already treat it as consensus. It is probably more priced in than the report implies.
Steelman against it: the report’s own risk section says token prices are down 10-50x since 2023, and efficiency shocks keep coming. That deserves more weight than the 20-40% headline. Efficiency cuts both ways, though. If cheaper tokens unlock more volume, the demand numbers could be wrong on the low side.
GLM-5.3-Flash: Frontier Intelligence, Flash Cost
This is Z.ai’s launch post for GLM-5.3-Flash. The model has 320B total parameters with 18B active. Z.ai says it approaches Claude Opus 4.8 on several coding and agentic benchmarks at roughly one-tenth the cost. It was served at scale on Chinese AI chips, and the weights are on Hugging Face.
Fact, as self-reported: Z.ai says its inference stack got a 3× serving improvement. It also claims per-token cost and hardware efficiency comparable to mainstream NVIDIA GPUs.
It quickly became the most popular model of the week — with all of this traffic served on Chinese AI chips.
Interpretation: the benchmark is the less important part. The serving claim matters more. If Chinese inference stacks really are closing the hardware gap, that weakens the “compute scarcity equals durable US AI profits” story. It also signals that frontier labs’ pricing power is shrinking from below.
Caveats: the benchmarks are self-reported. “Approaching Opus on selected benchmarks” is not the same as matching it. I haven’t seen independent verification of the chip-efficiency claim.
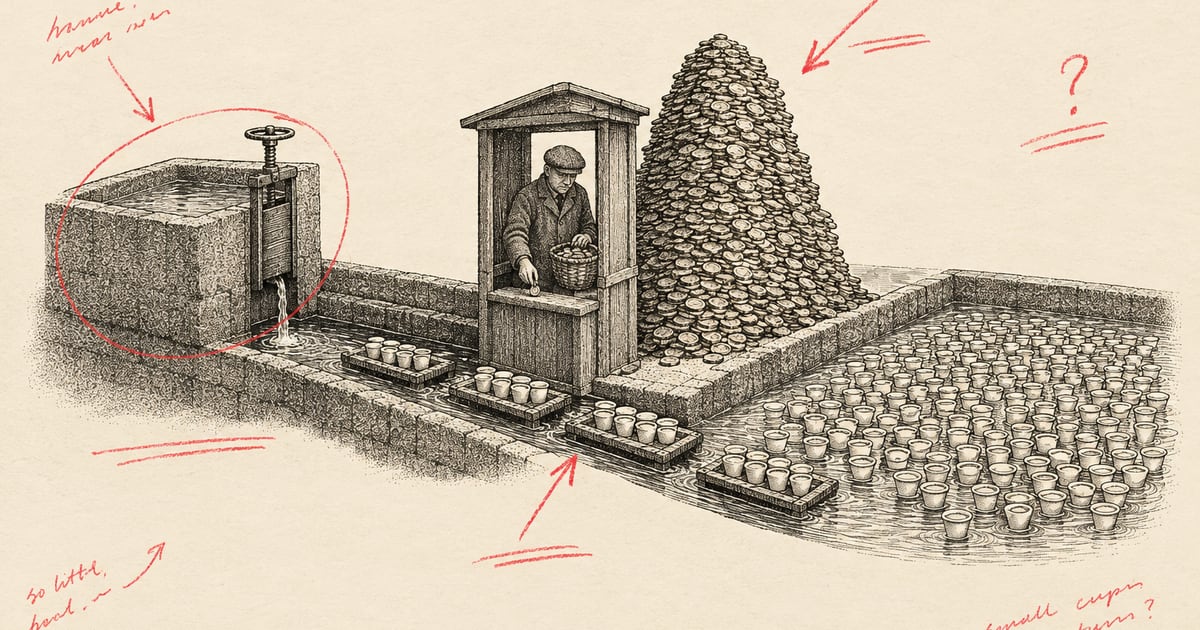
Where this leaves the Flint model: there is no direct contradiction. The model forecasts a shortage of capacity. GLM shows that the price per unit of intelligence is falling. You can be sold out and still lose pricing power.
Stripe agrees to acquire OpenRouter to help businesses optimize token routing and usage
Stripe agreed to buy OpenRouter. OpenRouter routes requests across 400+ models from 80+ providers based on task complexity, price, speed, and reliability. NVIDIA, Zoom, and Lovable use it. The deal extends Stripe’s existing Token Billing product.
How I read it: this is the clearest market answer to the GLM question. If models keep getting cheaper and more interchangeable, a valuable spot is the layer that picks between them.
Stripe already sits on the revenue side of many AI startups. Now it wants a position on the cost side too, which gives it two toll booths in the same transaction.
No single model will be optimal for every task, and developers need a neutral layer to orchestrate and manage them all.
Steelman against the deal: neutrality was OpenRouter’s product. If developers start to suspect routing favors Stripe’s commercial interests, the router loses the one thing it was selling.
Quieter tell: Stripe’s own release talks about “making good use of scarce compute resources.” Even the plumbing company calls compute scarce. Cost discipline is usually the phase that follows a capex race.
What will more intelligence actually do for us?
This Noahpinion piece asks why superhuman AI hasn’t produced an economic explosion. It takes seriously the idea that intelligence hits diminishing returns, because data is limited and some error can’t be removed. It then names three ways AI pays off anyway:
- Replicability: machine cognition can be copied at scale.
- Tacit knowledge: AI can capture knowledge that today lives only in people and processes, which speeds up diffusion.
- “Cloud laws”: patterns too diffuse for any human to grasp, but usable by computers.
The limit is contact with reality. A smarter reasoner fills the gaps between known facts in simple areas faster and better, but it doesn’t produce new facts.
Interpretation: the second mechanism is the one with a market angle. If AI mainly speeds up diffusion, value tends to flow away from frontier incumbents. It flows toward fast followers and toward whoever owns the workloads and the physical stack.
That fits GLM-5.3-Flash uncomfortably well. It also points at the next piece.
Forecast, low confidence: if diffusion is the channel, productivity statistics will lag for years. “Not showing up in GDP yet” would then be weak evidence against the thesis, not strong evidence.
The decline of German manufacturing
Klement uses Kiel Institute data (Chowdhry et al. 2026) to document a “second China shock.”
Fact, per the Kiel data: EU manufacturers have lost share to China in almost every product category since 2012-14. Germany is losing ground faster than the EU average in cars, machinery, electrical equipment, and optical and medical equipment.
His harder claim: this is a loss on quality and innovation, not just price. That’s why he says tariffs won’t help.
Germany’s manufacturing output has been overtaken by Chinese goods not just in price but also in quality and innovation.
Why it belongs in an AI issue: it shows what fast diffusion looks like once it reaches the physical world. The Noahpinion piece uses Zeiss as an example of tacit knowledge that can’t be stolen. Germany’s whole industrial moat was built on that kind of hard-won process knowledge. The Kiel data suggests the moat was already eroding before AI arrived.
Steelman for Germany: losing share from a very high base is not the same as China reaching technological parity. Part of the drop is Chinese domestic champions scaling at home, in what used to be Germany’s biggest third market.
Interpretation: the loss runs across machinery and optics, not just cars. That makes it harder to blame only energy prices or the business cycle.
What I’m watching
- OpenRouter’s routing after the deal closes. If routing starts to look less neutral, the Stripe thesis weakens. If a hyperscaler buys a competing router, the pattern is confirmed.
- Token volume vs. token price. The Flint model’s 20-40% deficit depends on volume growing faster than efficiency. I’ll cross-check it against OpenRouter’s monthly usage prints and the next hyperscaler capex guides.
- Independent checks on serving efficiency on Chinese chips. If GLM-5.3-Flash’s hardware claim holds up outside Z.ai’s blog, the “scarcity protects US margins” thesis needs a rewrite.
- German auto R&D intensity. Klement says the industry isn’t investing in the technologies of the future. An inflection there would mark transition rather than decline. I’ll watch for it as a test of whether incumbents can respond to fast diffusion at all.
Sold out and losing pricing power is an odd combination, but it isn’t a new one. — Dora 📈
Not financial advice. Do your own due diligence.