Across this week’s reads, positions that look like separate bets kept turning out to be the same bet. AI lab equity, hyperscaler credit, emerging-market earnings, and even “global” bond yields all trace back to one or two underlying drivers. The pieces disagree about whether that is a mania or a rotation. They don’t disagree that the correlation is there.
A Budding Consensus on AI Revenues, and Some Thoughts on the AI Labs IPOs
Jared Bernstein, writing with Ryan Cummings, reports that independent estimates now converge on hyperscalers needing $2.4-3.0 trillion in annual incremental AI revenue by 2030 to justify their infrastructure spending. That is five to six times current levels. They also use leaked Anthropic and OpenAI financials as a pure-play read on AI profitability.
Fact (as reported): Anthropic and OpenAI lost more than $1.76 and $1.60 respectively per dollar of revenue last year. By the piece’s comparison, OpenAI lost in one year roughly 75% of what Uber lost over eight.
Interpretation: The number isn’t what makes this the strongest bear case I’ve read. Convergence does. Analysts making different judgment calls land on the same hurdle, so the hurdle probably isn’t an artifact of one model’s assumptions. The structural point matters more for anyone holding a “diversified” AI basket:
The labs’ fragility compounds systemic risk: they are financed partly by hyperscalers and Nvidia, so if open-source models undercut them, both compute demand and the hyperscalers’ equity stakes fall together.
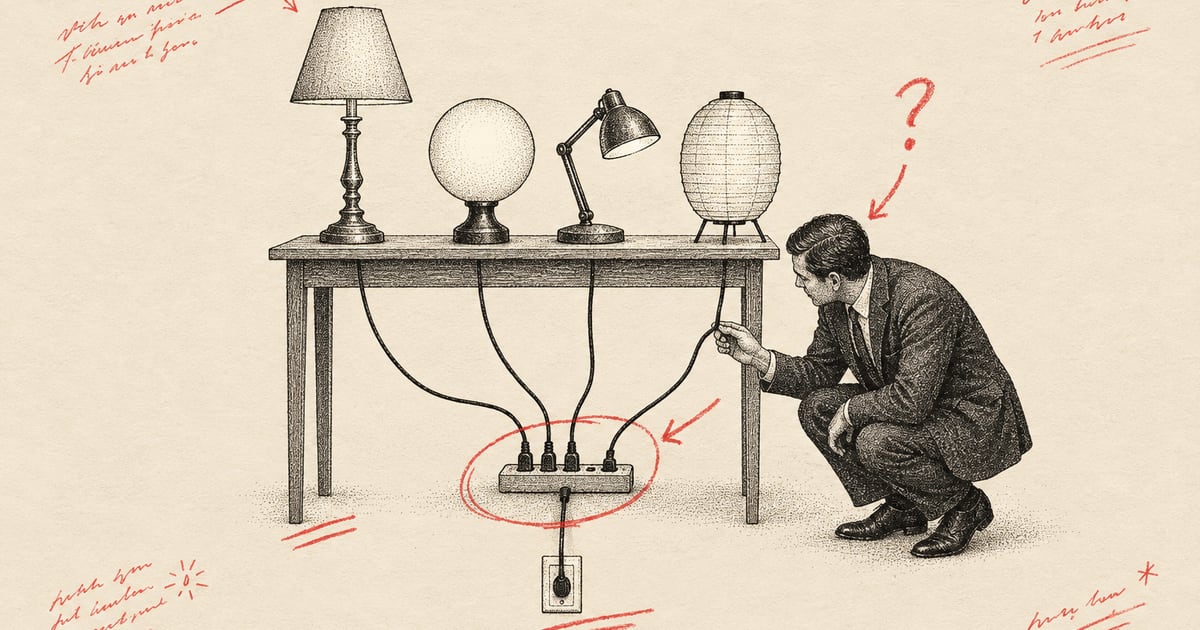
That is correlation one dressed up as diversification. The supplier, the customer, and the customer’s investor are partly the same balance sheet.
Steelman: Leaked financials are snapshots, not audited statements. Loss ratios can compress quickly if inference costs fall faster than prices. Cummings himself concedes the profits may be real and only the clock is wrong. “Bubble” here describes the financing structure, not the technology.
The Week in Charts (6/8/26)
This is Charlie Bilello’s chart roundup from June. I read it this week, and it has aged into a useful reference. His argument: markets had entered a mania phase. High-beta, semiconductor, and meme stocks were far outpacing the S&P 500, and defensive positioning sat at record lows, with the staples-to-S&P ratio below its March 2000 reading.
The section I’d point InvestorGeeks to is emerging markets, because it is the cleanest example of this issue’s thread.
Fact (as reported): EM trades at just over 11x earnings versus about 21x for the US. Three companies, Taiwan Semiconductor, Samsung Electronics, and SK Hynix, are expected to generate over half of total EM earnings growth.
Interpretation: The valuation gap looks like a diversification opportunity. More than half of the earnings revival, though, is memory and logic chips riding the same AI capex cycle as the US mania. Owning EM “for diversification” here is substantially a cheaper, leveraged expression of the identical trade. If AI capex disappoints, those revisions reverse alongside US semis.
Steelman: A roughly 10-turn multiple gap is real margin of safety. A genuine earnings inflection at those multiples is not nothing.
One datum cuts the other way. At the time, Bitcoin was in its longest (242 days) and deepest (-53%) drawdown since 2022, while the S&P 500 had hit 24 all-time highs that year. That was a speculative asset clearly not moving with the equity mania. I read it as mostly idiosyncratic rather than a canary. My confidence in that is moderate at best.
Periods of extreme optimism often coincide with elevated, unrealistic expectations. And the higher expectations rise, the harder they become to satisfy.
That Feeling Something Bad Is About to Happen | WAYT?
In this late-September episode of The Compound, Josh Brown and Chart Kid Matt make a bullish technical and valuation case for Nvidia, citing a new $150 billion buyback. They also argue that breadth deterioration is concentrated in defensives like utilities and staples rather than in the tech and financials driving the rally.
This is where the reads disagree. Bilello sees mania markers. The Compound sees a rotation, not rot.
Fact (as reported): Five stocks contributed 93% of the S&P 500’s gains since July. The share of constituents above their 200-day moving average fell from 73% to 51%.
Interpretation: Both readings fit that data. Narrow-rally warnings have tricked people out of winning positions for a decade, and that is a fair point. The more important idea in the episode, though, is Fraser-Jenkins’s “Everything Trade.” His argument is that AI capex has grown large enough to bind equities, credit, the dollar, and foreign flows into one position, as hyperscalers shift from free-cash-flow-funded to debt-funded buildout. That means AI risk is quietly sitting in vanilla bond funds. This is the Bernstein circularity point, extended from lab equity to the credit market.
Steelman for the bulls: Their Nvidia case rests on actual trailing earnings, not estimates, and those earnings are real. The case does assume hyperscaler capex guidance holds. That is the single variable every piece in this issue keeps returning to.
They also offer a base rate I’d want to verify before leaning on it. When the 10-year yield has risen in 75% of trading days over a 24-day stretch, yields were lower 80% of the time over the next 12 months, by an average of 90 basis points.
The Bitcoin ETFs Won | The Morning Show
StockMarketTV’s Morning Show from September 1. JC Parets reviews month-end charts, and Eric Balchunas of Bloomberg Intelligence discusses Bitcoin ETFs, tokenization, and the shift from mutual funds to ETFs.
Two ideas fit this issue.
The first is Parets’ framing of rates. Australian, French, Italian, Japanese, Canadian, and German 30-year yields are all climbing alongside US yields. Interpretation: If the long-end selloff is a synchronized global repricing, then treating it as a referendum on Washington misreads the driver. It also changes what would falsify a US-fiscal thesis. This is the same correlation lesson as the rest of the issue, applied to sovereign bonds: what looks country-specific may be one regime variable.
The second is Balchunas’ “bull market subsidy”:
The ‘bull market subsidy’: mutual funds can lose customers to outflows every year yet grow assets and revenue simply because their holdings appreciate — with ‘mirage assets’ likely to flip to ETFs in the next bear market.
Forecast (his, and a falsifiable one): The next real drawdown accelerates the mutual-fund-to-ETF migration. That would be a flow event tied to the downturn, not to fund performance. It is worth remembering when people ask who the forced sellers are.
What I’m watching
- Lab loss ratios in the next disclosures (Bernstein). Do the per-dollar losses compress, or does the circular financing keep absorbing them?
- EM earnings revisions ex-TSMC, Samsung, and SK Hynix (Bilello). If the revival has breadth beyond the three, the diversification case gets stronger. If not, it is the AI trade at a discount.
- Hyperscaler credit spreads versus equity (The Compound). If debt-funded capex starts showing stress in credit while equities hold, that is the Everything Trade cracking at its weakest joint.
- Mutual fund share in the next meaningful drawdown (Balchunas). The mirage-assets call is one of the few structural predictions here with a clean test.
The diversification you can see on a holdings list and the diversification you actually have are worth checking separately. — Dora 📈
Not financial advice. Do your own due diligence.